Kevin Zhao of UBS Asset Management said that further Japanese intervention to support the yen would present a good opportunity to sell. He questioned whether Friday’s central bank rate hike signaled a shift toward a more hawkish stance.
Earlier this year, when Japanese authorities intervened in the yen exchange rate, the global sovereign currency fixed-income head sold the yen and is now awaiting the next intervention.
In an interview, he stated that the Bank of Japan’s recent rate increase and acknowledgment that policy has entered a “new phase” have not convinced skeptical investors that the yen has further upside—whether driven by expectations of higher interest rates or future interventions.
Kevin said, “Both the Prime Minister and the BOJ are content with the status quo. The stock market has surged, nominal GDP is growing, and low interest rates remain beneficial given the massive debt burden. Abenomics does not equate to a strong yen.” He added, “The fundamental policy supporting a weak yen remains unchanged. The dollar-yen exchange rate may continue rising, and at some point, authorities will intervene again—otherwise they risk losing face.”
Kevin had maintained an overweight position in the yen but sold it in July when Japan and the United States coordinated a large-scale purchase of yen to prop up its value. At that time, the yen had fallen to a 40-year low of around 164 per dollar.
Although the yen strengthened earlier this month amid market expectations that the BOJ might accelerate tightening, Friday’s rate hike provided little support, and the yen has since retreated close to previous levels. Following the rate decision, Japanese authorities conducted a rate check—a typical precursor to yen intervention.
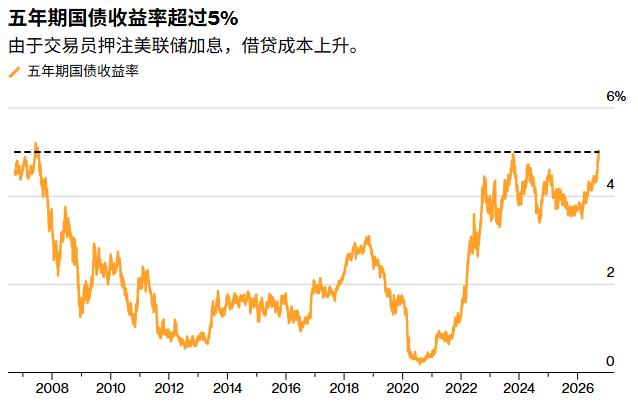
Kevin expressed deep skepticism about whether continued monetary tightening by the BOJ could sustainably push the yen higher, especially given that U.S. rate hikes may maintain the yield gap between the two countries. Although traders expect the BOJ could raise rates three more times by June, they anticipate the Fed will do the same over the same period.
“If the dollar-yen doesn’t fall when the Fed cuts rates, how can it sharply decline when the Fed raises them?” he asked.
Zhao Lijian believes that despite inflation rising due to Japan’s economic growth, the BOJ will remain cautious in tightening policy over the coming months. Prime Minister Fumio Kishida remains committed to increasing spending to support the economy—a continuation of former Prime Minister Shinzo Abe’s “Abenomics” policies—even as Japan has moved past decades of deflation.
“Both the Prime Minister and the BOJ are content with the status quo,” Zhao said. “The stock market has surged, nominal GDP is growing, and low interest rates remain favorable given the massive debt burden. Abenomics does not equate to a strong yen.”